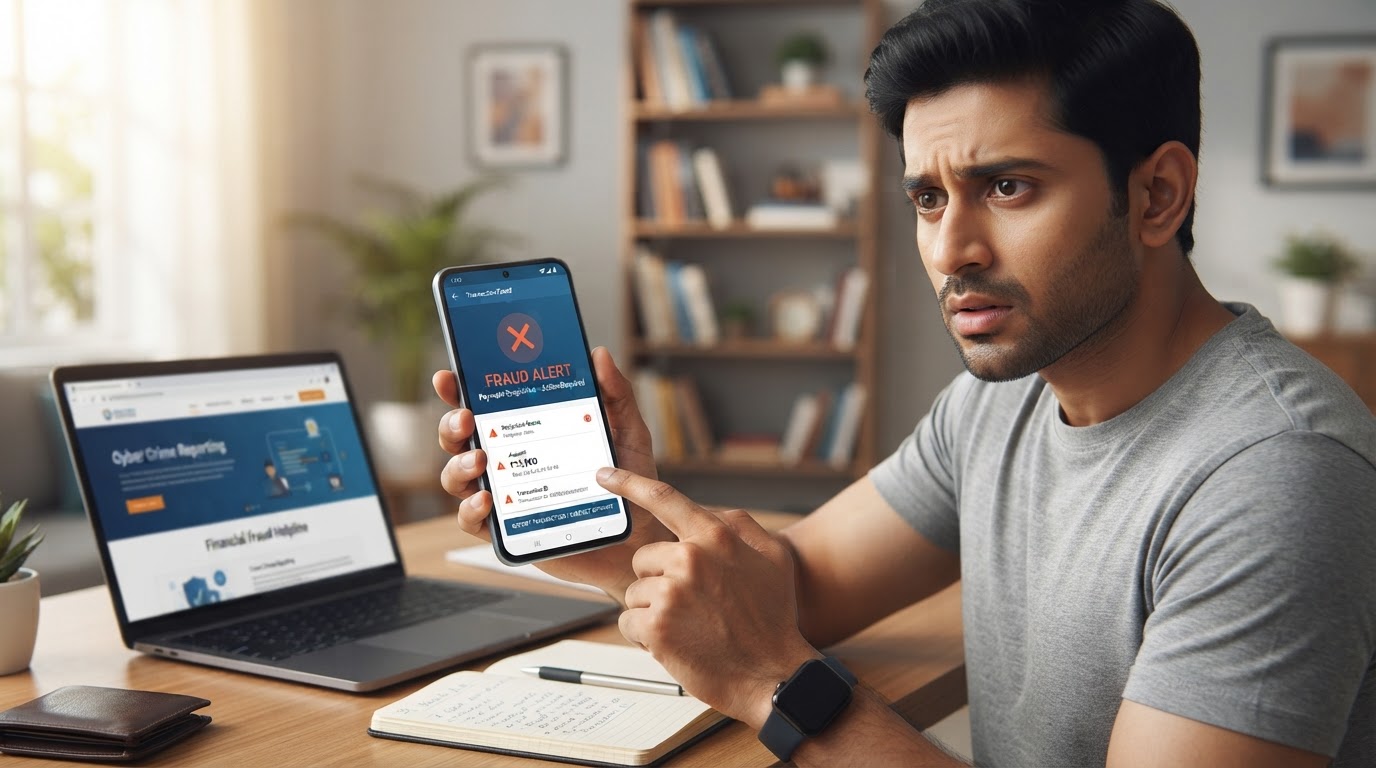
A UPI scam often becomes obvious only after the payment is complete: the seller disappears, a fake customer-support agent stops replying, or you realise a “collect request” actually sent money from your account. At that point, speed matters more than embarrassment.


NPCI states that once a UPI payment is initiated it cannot simply be stopped like an unpaid cheque. That does not mean you should give up. You should report the transaction immediately through the UPI app and your bank, preserve evidence, and report online financial fraud through India’s cybercrime system.
Step 1: Stop communicating with the scammer
Do not send a second payment because the fraudster claims it is needed for a “refund,” “verification,” “GST release,” “account unfreeze,” or “reversal fee.” Recovery scams often start immediately after the first loss.
If the scammer is asking you to install an app, share your screen, reveal an OTP, enter a UPI PIN, or click another payment link, stop. RBI has repeatedly warned users not to share PINs, OTPs or passwords and not to install unknown apps based on messages or calls.
Step 2: Save the UPI transaction details
Before deleting chats or blocking numbers, save the information that may help your bank and cybercrime authorities trace the transaction.
- UPI transaction ID or UTR/reference number
- Date and exact time of the payment
- Amount sent
- Recipient UPI ID, mobile number or merchant name
- Your bank account used for the payment
- Screenshots of the transaction status
- Chat messages, SMS, emails and call numbers used by the scammer
- Any website, QR code, social-media profile or advertisement connected to the scam
Keep the originals where possible. Do not edit screenshots in a way that removes timestamps, account names or reference numbers.
Step 3: Report the transaction inside your UPI app
NPCI’s UPI guidance says transaction complaints can be raised through participating bank UPI apps. Open the specific transaction and look for options such as Help, Raise Complaint, Report Fraud or Dispute Transaction.
The wording differs by app. Choose the most accurate reason rather than a random dispute category.
If the app only provides a chatbot or ticket number, save that ticket number. It can help show when you first reported the fraud.
Step 4: Contact your bank immediately
Use the official number shown in your banking app, on the bank’s website, or on the back of your debit card. Do not use a “customer care” number from a random search result, sponsored ad, WhatsApp message or social-media comment.
Tell the bank that the payment was induced by suspected fraud and provide the UTR/reference number. Ask the bank to register a complaint and give you a complaint or service-request number.
If your phone, SIM, banking credentials or device access may also be compromised, tell the bank. You may need to block cards, disable digital banking temporarily, change passwords or take other protective steps.
Step 5: Call the cybercrime helpline 1930
The Government of India’s National Cyber Crime Reporting Portal lists 1930 as the helpline for immediate reporting of online financial fraud.
Call as soon as possible. Be ready with your name, mobile number, bank details, UPI transaction reference and basic facts about the fraud.
Fast reporting can improve the chances that authorities and participating financial institutions can act on the money trail before funds move through multiple accounts. Recovery is never guaranteed, but delaying the report only makes the trail harder to contain.
Step 6: File a complaint on the National Cyber Crime Reporting Portal
After the urgent call, file the complaint online at the official National Cyber Crime Reporting Portal. Upload or enter the evidence you saved, including transaction details and scammer contact information.
Keep the acknowledgement or complaint number. If you later contact your bank again, refer to both the bank complaint number and cybercrime complaint number.
Can a UPI payment be cancelled after it is sent?
NPCI’s UPI FAQ says that once a payment is initiated, a stop-payment request is not available. UPI is designed for instant bank-to-bank payments.
This is why prevention is so important. If you authorised a payment to the wrong or fraudulent recipient, you cannot rely on a simple “cancel” button after the transfer completes.
However, reporting fraud is still worthwhile because banks and law-enforcement channels may be able to investigate the beneficiary account and movement of funds.
Do you need a UPI PIN to receive money?
No. RBI’s fraud-awareness material warns that you do not need to enter a PIN or password to receive money. If an app asks you to enter your UPI PIN to approve a transaction, treat that as authorising money movement from your side—not as a requirement for someone to pay you.
This is a common scam pattern on online marketplaces. A fraudster pretends to be a buyer, sends a collect request and tells the seller to enter the UPI PIN to “receive” money. The PIN actually authorises the payment.
Common UPI scam patterns to recognise
Fake customer support
A fraudster claims to represent a bank, UPI app, courier company, shopping site or telecom provider and asks you to install a remote-access app or share credentials.
Collect-request scam
You are told to approve a request and enter your UPI PIN to receive money. In reality, you are authorising a debit.
QR-code refund scam
The scammer says scanning a QR code will credit a refund. A QR code can be used to prepare a payment, so always read the final confirmation screen before authorising anything.
Fake KYC or account-block message
You receive an urgent message saying your bank or wallet account will be blocked unless you click a link and update details immediately.
Small payment followed by a larger request
A fraudster may first send or request a small amount to build trust, then create urgency around a much larger payment.
What if the UPI app says the transaction failed but money was debited?
That situation is different from a scam. NPCI says UPI supports real-time reversals for declined transactions and advises users to contact the bank if the amount is not reversed.
For a technical failure, use the transaction-status and complaint process in your UPI app. For a payment you knowingly authorised because of deception, report it as suspected fraud and use the cybercrime channels as well.
How to reduce the risk of another UPI scam
- Never share your UPI PIN, OTP, card PIN or banking password.
- Do not install remote-access apps because a caller asks you to.
- Verify customer-support numbers from the official bank/app website.
- Read the name and amount on the final payment screen before entering your PIN.
- Do not enter a UPI PIN to “receive” money.
- Be suspicious of urgent refund, prize, KYC or account-block messages.
- Keep your phone and banking apps updated.
What about new UPI merchant charges?
Fraud warnings should not be confused with legitimate payment-policy changes. If you are trying to understand merchant pricing, read our separate guide to UPI MDR and merchant charges from October 15, 2026. A scammer may use real financial news as a pretext, so verify any payment request independently.
Final checklist after a UPI scam
- Stop sending more money.
- Save UTR/reference numbers and screenshots.
- Raise a complaint in the UPI app.
- Contact your bank through an official channel.
- Call cybercrime helpline 1930.
- File the complaint on the National Cyber Crime Reporting Portal.
- Secure your phone, SIM and banking credentials if they may be compromised.
Do not pay anyone who promises guaranteed recovery for an upfront fee. Use your bank, the official cybercrime system and legitimate law-enforcement channels.
Sources and further reading
- NPCI: UPI frequently asked questions
- National Cyber Crime Reporting Portal
- RBI: Public awareness on payment frauds